


I. Industry Panorama: Already the World's No. 1, Yet "Big but Not Strong"
As of 2025, China's domestic composite materials output has exceeded 8.1 million tonnes. The country's carbon fiber capacity accounts for about 50% of global capacity, firmly ranking first, while glass fiber annual capacity has surpassed 8.43 million tonnes, accounting for over 70% of the world total. In terms of scale, China is already the world's largest manufacturer of composite materials.
But "big" does not equal "strong". The industry's most prominent contradiction today is overcapacity in commodity products intensifying price competition, while high-end products remain in short supply and partially dependent on imports - a typical coexistence of "structural overcapacity and a high-end shortage". At the critical juncture of the start of the "15th Five-Year Plan", simply continuing the old path of "expanding capacity and adding production lines" is no longer sustainable.
Reviewing the 15 representative composite-material-related A-share listed companies at the top of the industry - they cover almost all major segments, including carbon fiber, glass fiber, electronic copper-clad laminates (CCL), aviation composites and modified plastics, and each has moved from a single core business to multi-track operations after listing. Through their trajectories, the industry's logic comes clearly into view.
Table 1. Listing Timeline of the 15 Representative Companies
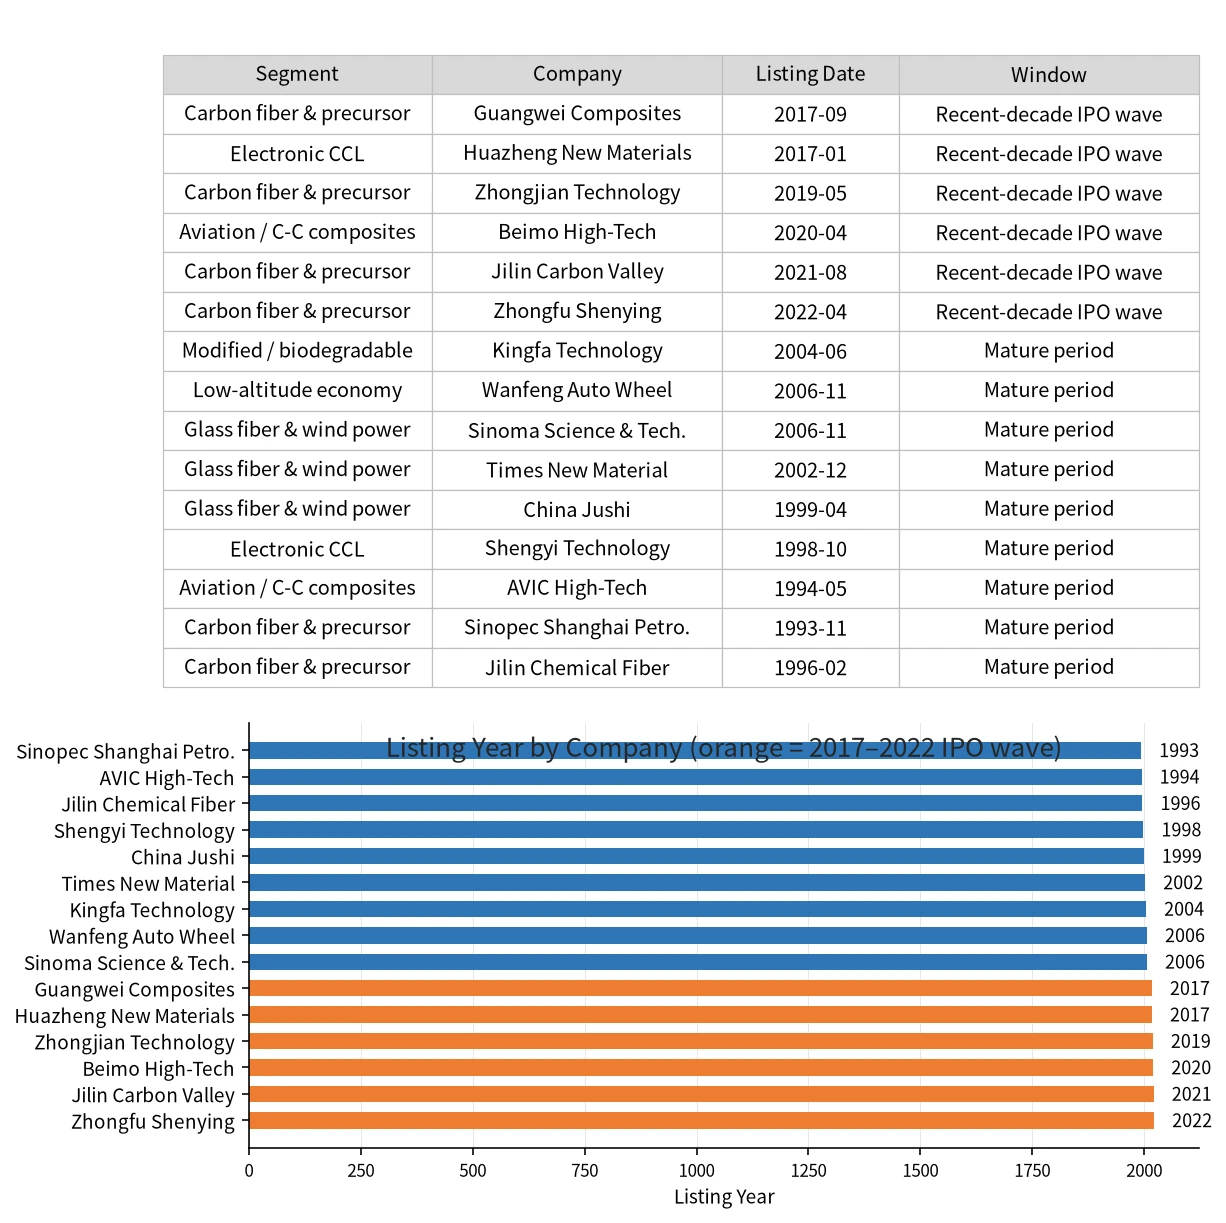
As shown above: 2017–2022 was the most capital-intensive five-year window, all of which landed on "carbon fiber + carbon-carbon brakes + CCL newcomers"; carbon fiber jumped from 0 to 6 A-share listings. The leaders in glass fiber, modified plastics, aviation composites and electronic CCL all listed before 2010 - mature existing sectors where the opportunity lies in "concentration gains" rather than "listing dividends". The carbon fiber listing dividend has been fully realized; with six players competing on the same stage, the industry beta is shifting from "scarcity premium" to "capacity competition".
[To be continued: Composite Materials Industry: From "Capacity First" to "Value First" (Part II)]
[Source] China Composites Industry Association official website (CCIA)
[Original Link] https://www.ccia.xin/xingyebaogao/3626.html